Invesfera Newsroom
The market now pays for profits on the books, not stories
After a rough week for AI stocks, money is moving toward companies that book earnings today. We think that is sensible, but it isn't a free pass for price-driven growth.
After a rough week for AI stocks, money is moving toward companies that book earnings today. We think that is sensible, but it isn't a free pass for price-driven growth.
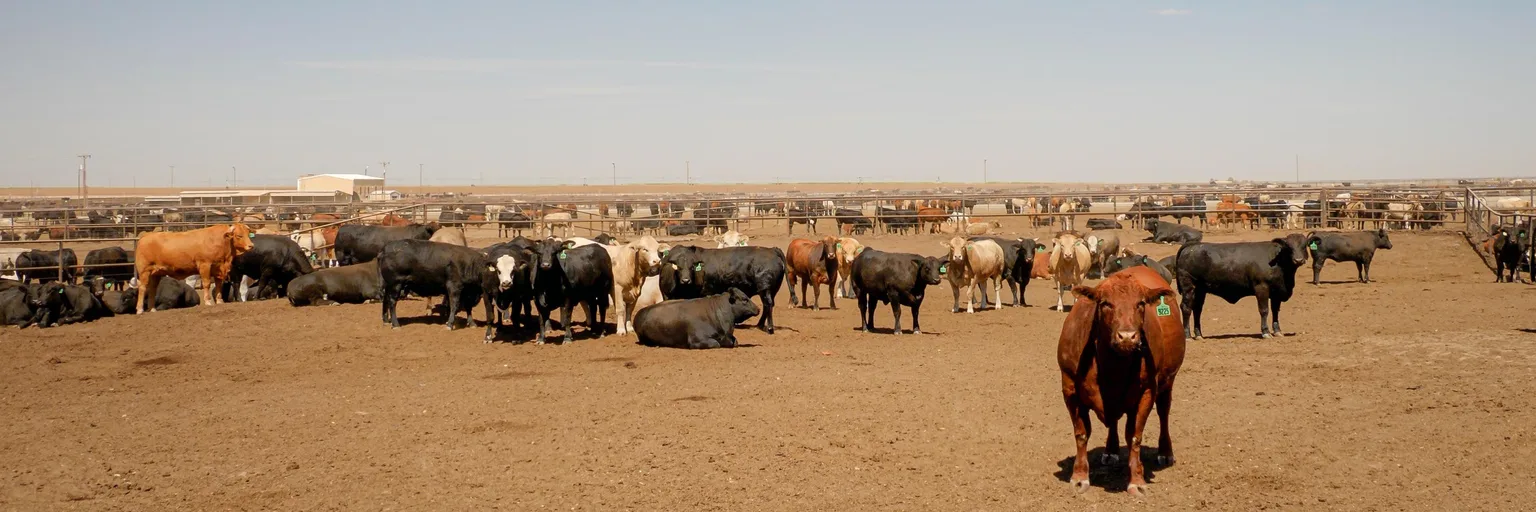
A Fort Worth jury convicted two brothers in a $240 million cattle Ponzi. The lesson isn't to avoid tangible assets. It's that a story about an asset proves nothing.
At $70-$78 a share, Anthropic's debut prices in flawless growth, huge compute bills and benign markets. Size any position as a bet on the price, not a lottery ticket.
A quarter-point hike is mostly priced in. The sensible response is a check on bond duration, cash yield and leverage, not a portfolio overhaul driven by a headline.
A 57% drop in short interest on TFLR says little about rates. Floating-rate loans pay more when the Fed hikes, but they carry credit risk and are no safe haven.
OpenAI is reportedly seeking $20 billion instead of $30 billion at a lower valuation. It's no collapse, but it's a reminder that private AI marks are negotiated prices, not facts.
SCHD deserves a place in many portfolios, but 7% yield stories blur the trade-off between income, total return and concentration. Treat it as a core piece, not a promise.
Vertiv's 61% sales growth and GE Vernova's near-$200 billion backlog suggest AI spending is flowing to power and cooling suppliers, but position size matters more than the story.
Volatility feeds exchange operators, and Deutsche Börse's 40% one-year rally shows investors know it. But a price near its yearly high means the good news may already be in the quote.
Stocks have overtaken housing as America's top wealth driver for the first time since WWII. We think that's less a triumph than a concentration risk, unevenly shared.
Stocks hit 48.2% of Americans' financial assets, above the dot-com peak. Rallies feel great, but that concentration is a risk to check against your own horizon.
The world's largest sovereign fund posted a $29.7 billion quarterly loss as bonds slid, and the lesson for ordinary savers is about what bonds are actually for.
Index funds still work, but the top 10 stocks now carry roughly 40% of the S&P 500. Check your exposure before you assume you're diversified.
SCHG beat VOO by 134 points over ten years, but the lead came early, the last year went the other way, and the real question is how much growth you already own.
Eni doubled its quarterly profit and added a €0.46 special dividend. Great for holders, but the payout is built to flex with commodity prices, so treat it as upside.
AT&T and Super Micro show that growth is only the first hurdle; the real winners will convert infrastructure spending into durable cash flow and margins.
Iberdrola is scaling the energy transition, but its €10.1 billion investment test is whether networks and renewables can turn capital into durable returns.
For long-term investors, the real measure of a dividend stock lies not just in its yield, but in its robust free cash flow, consistent payout ratios, and an unshakeable economic moat.
ExxonMobil and Chevron, traditional energy giants, are pursuing vastly different strategies for future growth, prompting investors to weigh long-term value against higher yields and new ventures.
European professional investors are increasingly embracing active ETFs, signaling a fundamental shift from traditional passive strategies towards more dynamic and nuanced investment management.