Invesfera Newsroom
Markets are priced for endless AI spending, and pharma can't catch the fall
The day AI capex flattens is the real test for stocks. In our view, the defensive rotation already under way is less independent of AI than it looks.
The day AI capex flattens is the real test for stocks. In our view, the defensive rotation already under way is less independent of AI than it looks.
Seasonal patterns say the best stretch for stocks starts now. But base rates ignore concentration, valuation and today's yields, and steady contributions beat guessing the bounce.
Midterm headlines will be loud on November 3, but the evidence suggests that Treasury yields, deficits and earnings matter more to your portfolio than who wins.
Big Tech is returning the smallest share of its cash in at least 15 years because AI capex eats it first. Investors should watch growth and free cash flow, not payout habits.
When the Nasdaq slips, the most hyped AI names must lower their asking price. Retail investors should read that as a caution about IPOs and private marks, not as an invitation.
Markets expect one more Fed hike in December, but two officials are already arguing for more, so savers should plan for a plateau with an exit risk.
Brent in the low-to-mid $110s tempts investors to chase energy. We think the bigger risk is what dearer fuel does to inflation and to the path of interest rates.
FTSE Russell's reclassification brings index money to Vietnam almost automatically, but foreign investors are still net sellers. Lasting capital will depend on reforms, not on a label.
Tech fell, Treasuries rallied and oil hit six-month highs on the same day. The market is pricing AI cash burn, not just rates, so check what your bonds really do for you.
The Nasdaq's 747-point slide, driven by AI worries and an Intel plunge, is a reminder that "diversified" index funds can hide big bets on a few names. Check before you react.
With a war, spiking oil and falling yields, gold still hit a one-year low. It is trading on rate expectations, so savers who bought it as insurance should check what they own.
Intel beat on profit and still suffered its worst day in decades, while Amazon missed. The lesson for index-fund owners is how much one AI narrative is carrying.
Wall Street didn't reject AI this week. It rejected spending that arrives long before the profits do, and index-fund holders are more exposed to that than they think.
Amazon, Intel and Alphabet shook the Nasdaq while most S&P 500 sectors held up, so the real question is not whether AI is a bubble but how much of your portfolio rides on one trade.
Intel beat on earnings and still lost about a fifth of its value after a weak forecast. Recovery stories get priced for perfection, and guidance is where the bill arrives.
Japan's central bank stood still at 1.25% but raised its 2027 inflation forecast. Treat that as a deposit on the next hike, and check your exposure to cheap-yen leverage.
AWS grew 39% and sales rose 12%, yet shares sank: the market now wants proof that heavy AI capex turns into cash, and index investors should notice.
By leaving nine months early, Lagarde starts a political race for the ECB just as France's debt is stressed and rate hikes remain possible. Governance may now be a priced risk.
A cloud business that doubled couldn't save Alphabet's stock from a search miss and negative free cash flow. Investors have stopped funding AI capex on faith.
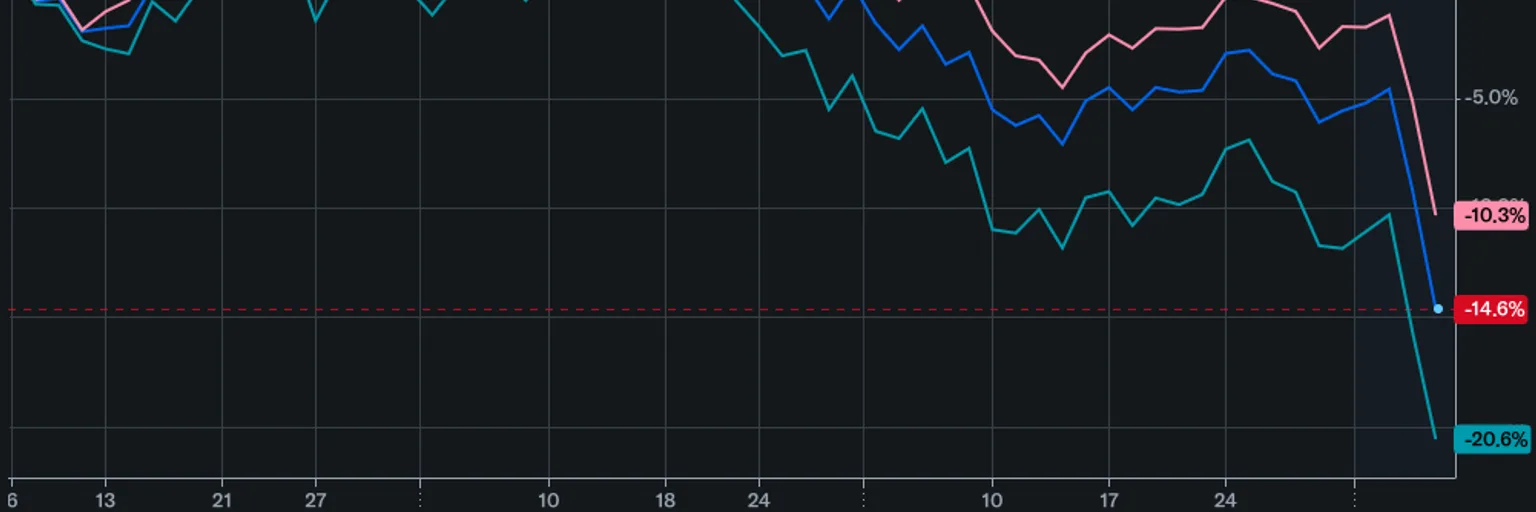
The STAR50 rout shows how fast an AI premium can evaporate when expectations outrun profits. The real question is how much of your portfolio rides on the same story.