Staking inside crypto funds just got easier, but the IRS still wants its cut
Rev. Proc. 2026-20 gives crypto trusts a path to staking without losing grantor trust status. Rewards are generally ordinary income, so judge the yield after tax.
AI-generated image
Is a yield still a yield if a big slice of it goes to the tax authority the moment it lands? That is the question to ask now that the IRS has made staking inside crypto funds, in our view, a lot more respectable.
The news is Rev. Proc. 2026-20. As KPMG describes it, it is a safe harbor for trusts that otherwise qualify as investment trusts. Follow its conditions and a trust can stake without losing its investment-trust and grantor-trust status. One tax firm counts 14 steps in the safe harbor. It also updates an earlier safe harbor: per Thomson Reuters, a trust that complied with Rev Proc 2025-31 can keep relying on it for up to six months after October 6, 2026.
A clarification, because the numbering invites confusion: Revenue Ruling 2026-20 and Notice 2026-62, issued September 28, 2026, are a different matter. They deal with aggressive multi-step ETF transactions, not staking. Same number, different document.
This is a green light for the structure, not for the yield
We think the headline "IRS clears the way" is accurate and slightly misleading at once. It is accurate because, in our view, tax-status uncertainty was probably one of the biggest obstacles to staking in a fund wrapper, and a safe harbor removes a good part of it. It is misleading because it says nothing about how pleasant the tax bill will be.
The tax sources we reviewed point the other way. Staking rewards are taxable as ordinary income when received, according to an advisor-focused tax guide, valued at fair market value at that moment, and it does not matter that you did not sell. The IRS itself tells individuals to report income from forks, staking and mining on Schedule 1 of Form 1040, while sales of digital assets go through the capital gains forms. Two different tax buckets, and the staking one is the less friendly. How that plays out for investors in a specific trust is something we cannot confirm from these sources.
Ordinary income versus capital gains is the whole game
Here is why the distinction matters. According to Schwab, the federal ordinary rate tops out at 37%, while long-term capital gains are taxed at 0%, 15% or 20% depending on income. High earners can also face an extra 3.8% net investment income tax. Those figures come from Schwab's discussion of fund distributions, not from the staking guidance. We use them only to show the gap between the two tax buckets.
Do the arithmetic for a top-bracket investor. Of every $100 in staking rewards, up to $37 may go to federal tax before state tax or the surcharge. Meanwhile, price appreciation held more than a year gets the gentler treatment. In our view, that flips the usual pitch. Staking is sold as extra return on top of owning the coin. For a taxable investor, it can be extra return taxed at the worst rate, on a schedule you do not control.
Two more wrinkles deserve caution. The safe harbor, as summarized by one tax blog, requires that rewards consist solely of additional units of the same single digital asset. We do not know from the public summaries how each trust will handle those units or whether investors will receive cash to pay the tax. That is a question for each fund's prospectus. If a fund recognizes income without paying out cash, the investor's "yield" may arrive as a tax bill. We are flagging a risk, not reporting a fact about any specific product.
What a sensible investor should do
Who wins? Fund sponsors, probably: they get a legal path to a more competitive product. Investors in tax-advantaged accounts may also come out well, though the treatment of any specific account type is something to confirm with a professional, because the sources we reviewed do not settle it. Who loses? Taxable investors who read a headline staking rate as money in the pocket.
Our recommendation is plain. Compare any staking-enabled fund on after-tax yield, using your own marginal rate, and subtract the fund's fees. Ask whether the staking income is passed through to you and how. Staking carries its own risks too, but the material we have is about tax, and tax is where the surprise hides.
This is not personalized advice, and rules differ by country. Everything here concerns US federal tax. In our reading, the IRS has made staking in a trust easier to offer. It has not made it free. Treat the reward as a taxable item first, and only then decide whether it is worth having.
No topics yet: start the first one.
More stories
Sparkasse's Bitcoin Embrace: Legitimacy Amidst Volatility
Germany's savings banks are rolling out Bitcoin trading to retail customers, a move that could mainstream cryptocurrency, despite clear warnings about its inherent risks.
MiCA isn't just a new rule: it's crypto's new financial order
The EU's MiCA regulation has fundamentally reshaped the cryptocurrency landscape, demanding unparalleled transparency and shifting power towards regulated entities and investor protection.
Visa Direct's Stablecoin Leap: A Glimmer of Hope for Global Payments
Visa's transition of stablecoin payments from pilot to commercial production marks a pivotal moment, promising efficiency and accessibility for cross-border transactions.
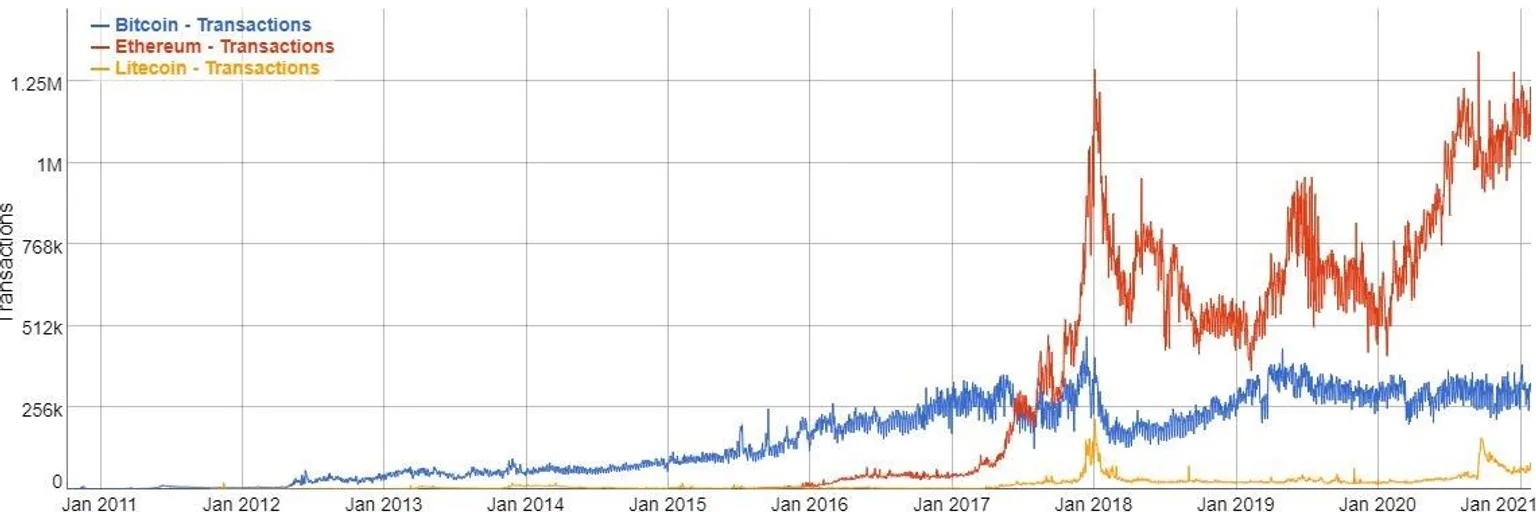
Beyond the Noise: What Bitcoin's On-Chain Data Really Shows
While Bitcoin's price movements captivate headlines, true insight for investors lies in understanding on-chain data, which reveals network health and investor behavior.